How to Fill Out Schedule C for Realtors, 2026: The Income Side First (Line 7)
This is education, not tax advice. I'm not a CPA or EA. State taxes are not covered.
Schedule C, Schedule 1, and Schedule SE cited below are IRS draft as of 2026-10-07 — DRAFT, NOT FOR FILING. If a line changes, this page is updated in place with a dated note at the foot of the article.
- Last checked
- Tax year
- 2026
- Core line
- Schedule C, line 7 — gross income
- Changes
- Update log (1)
§1One job, one tax year, one line
One job, one tax year, one line. The job is real estate agent. The year is 2026. The line is Schedule C, line 7 — gross income, the number Part I of this form builds out of a year of commissions before one expense line is read.
The first four articles read the forms that surround this one — estimates, the self-employment tax on the profit, the income no form reported, the annualized catch-up. This article opens the job forms, and it reads the whole of this one: where the commissions land, which printed expense lines carry a realtor's year, and where the profit goes when the form is done.
§2Where the commissions land: lines 1–3
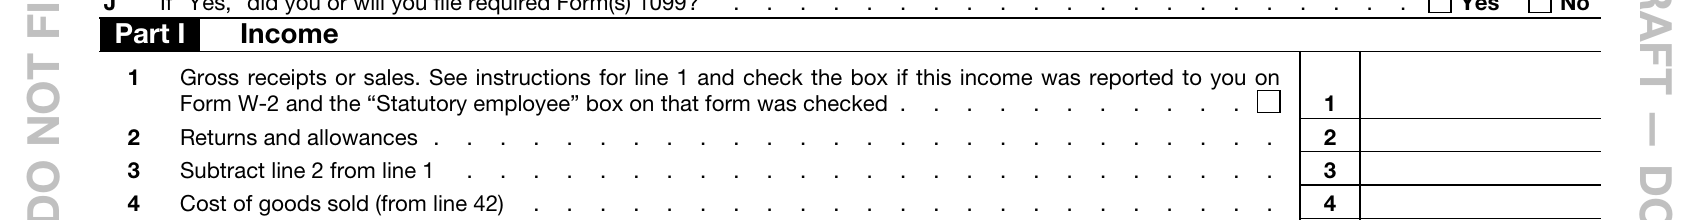
Part I of Schedule C is the income side, and it is seven lines long. It starts at line 1: gross receipts or sales.
For a real estate agent, the year's commissions are the gross receipts. In this article's worked example — hypothetical numbers, used only here — the commissions are the amounts reported on Form 1099-NEC from the brokerage, and line 1 is $112,000 of commissions. But read what line 1 asks for: the receipts themselves, the total the business took in.
Line 2 is returns and allowances: amounts given back. This example has none, so line 2 is zero. Line 3 subtracts: line 1 minus line 2. $112,000 minus zero is $112,000, and that figure is what the next three lines work on.
Notice the order the form uses. It does not ask what the agent spent, or what the agent kept. It asks what came in, what went back, and only then starts building toward income.
§3Lines 4–7: the core line
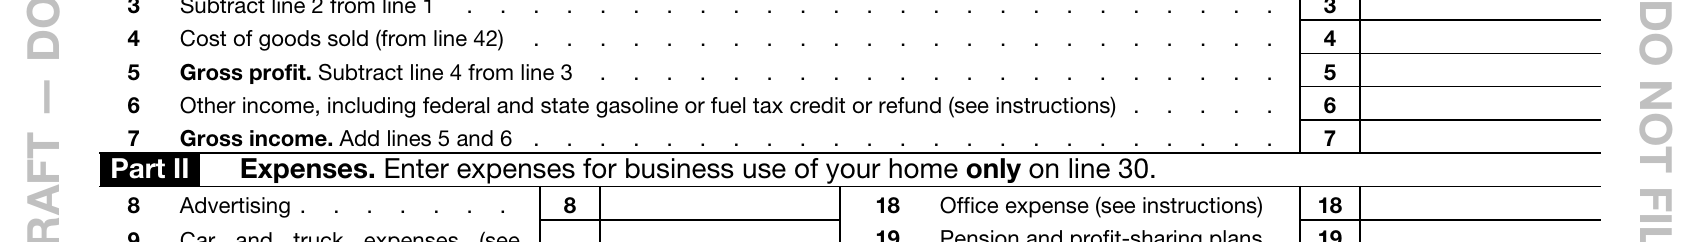
Line 4 is cost of goods sold, and it does not live on this page — it is figured in Part III of the form, the inventory section, and carried up from line 42. A commission business holds no inventory, so in this example line 4 is zero. Line 5 is gross profit: line 3 minus line 4. $112,000 minus zero — $112,000.
Line 6 is other income: income of the business that is not in the gross receipts. This example has none; line 6 is zero.
Line 7 adds line 5 and line 6. $112,000 plus zero is $112,000. That is gross income — the core line of this article. Read what it is made of: receipts, minus what was returned, minus cost of goods sold, plus other income. Nothing on lines 1 through 7 has asked about an expense of running the business. Every expense lives below this line, in Part II — and line 7 will not change when we get there.
§4The expense block: lines 8–27b, with the example's amounts
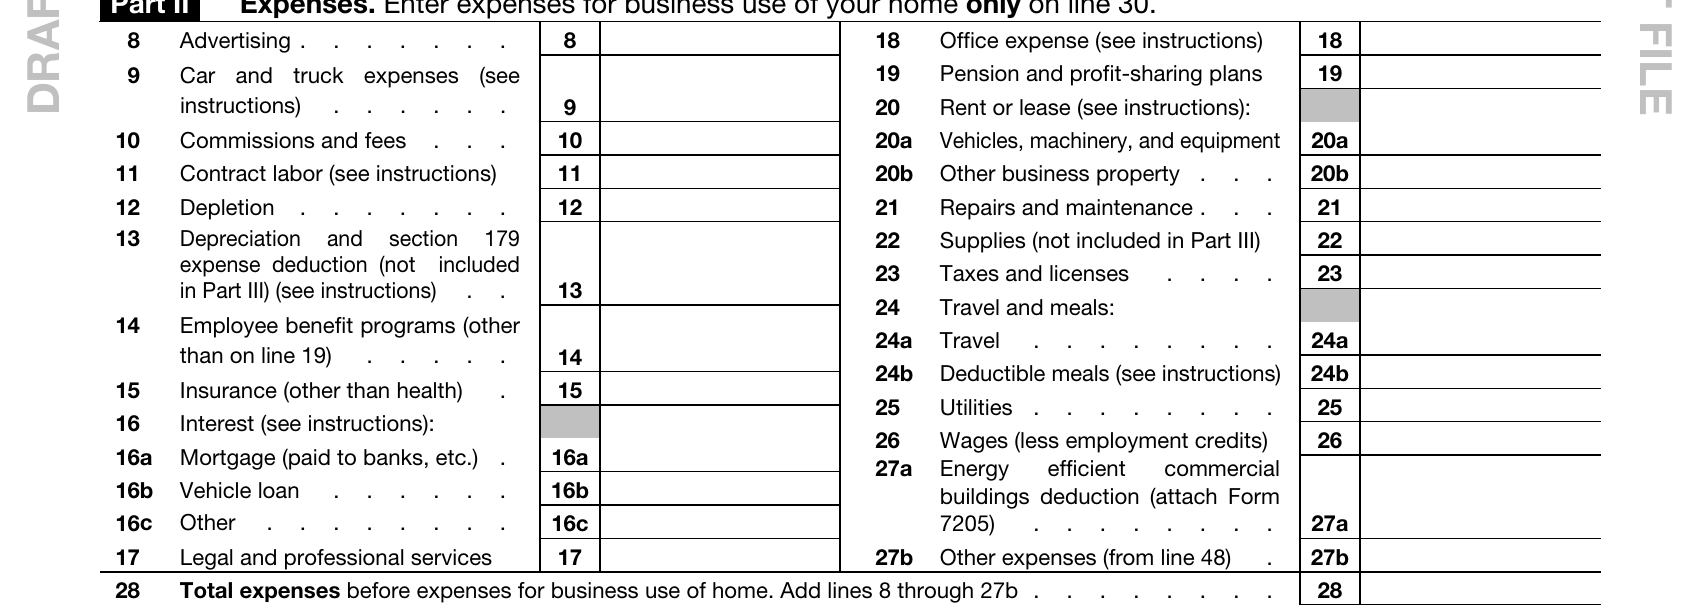
Part II is the expense block: printed lines, each with a label, running from line 8 to line 27b. This article reads the lines that carry a realtor's year, with the worked example's amounts.
Line 8, advertising: $3,240. Line 9, car and truck expenses: $8,910 — an entered amount only. How a figure like that is built, mileage against actual cost, is its own article later this season; here the number is read as it sits on the line. When line 9 is claimed, the form also asks vehicle questions in Part IV — placed-in-service date, miles split three ways, whether written evidence exists. Those questions are printed on this form; they are not read line by line here.
Line 10, commissions and fees: $6,300 — what this agent paid out to others inside the deals. Line 11, contract labor: $2,400. Paying contractors also meets two questions printed at the top of this form — the header asks items I and J, about payments that would require filing Forms 1099. They get one mention here; the full read of those two items belongs to the designer-consultant article, where paying a subcontractor is that job's own expense line.
Line 18, office expense: $1,980. Line 23, taxes and licenses: $650. Line 27b, other expenses: $1,120 — and 27b is a carried figure: the expenses behind it are listed in Part V of the form and totaled at line 48. In this example that listing is the agent's MLS and association dues, $1,120 — listed in Part V and carried to line 27b through line 48, because this example places them there. The form prints the route — list in Part V, total at line 48, carry to 27b — not a category for dues.
Those are the only expense lines this example uses. The block holds more lines — insurance, legal and professional services, rent, wages — and every one of them reads zero here, because the example claims only what is on the page.
§5The Fork: two totals that never read each other
Split card — Line 7: built from lines 1–6 only; Line 28: built from lines 8–27b only; a wall drawn between the two columns.
Here is the fork in this form, and it is structural: Part I and Part II each build exactly one total, and neither total is figured from the other.
Line 7 is built only from the income side. Receipts in, returns out, cost of goods sold, other income. No expense line reaches up into it — line 7 would be $112,000 in this example whether the expense block below it totaled ten thousand or forty thousand.
Line 28 — the total we are about to reach — is built only from Part II: the expense lines actually printed on the form, added as they sit. It does not read line 7. It does not know whether the year was large or small. It is the sum of lines 8 through 27b, nothing else.
So the form keeps two piles separate until a single subtraction near the bottom: an income total built from records of what came in, and an expense total built from the printed lines. What the business actually made is on neither total. It is the distance between them — and the form computes that distance in the next three lines.
§6Lines 28–31: the answer, and where it goes
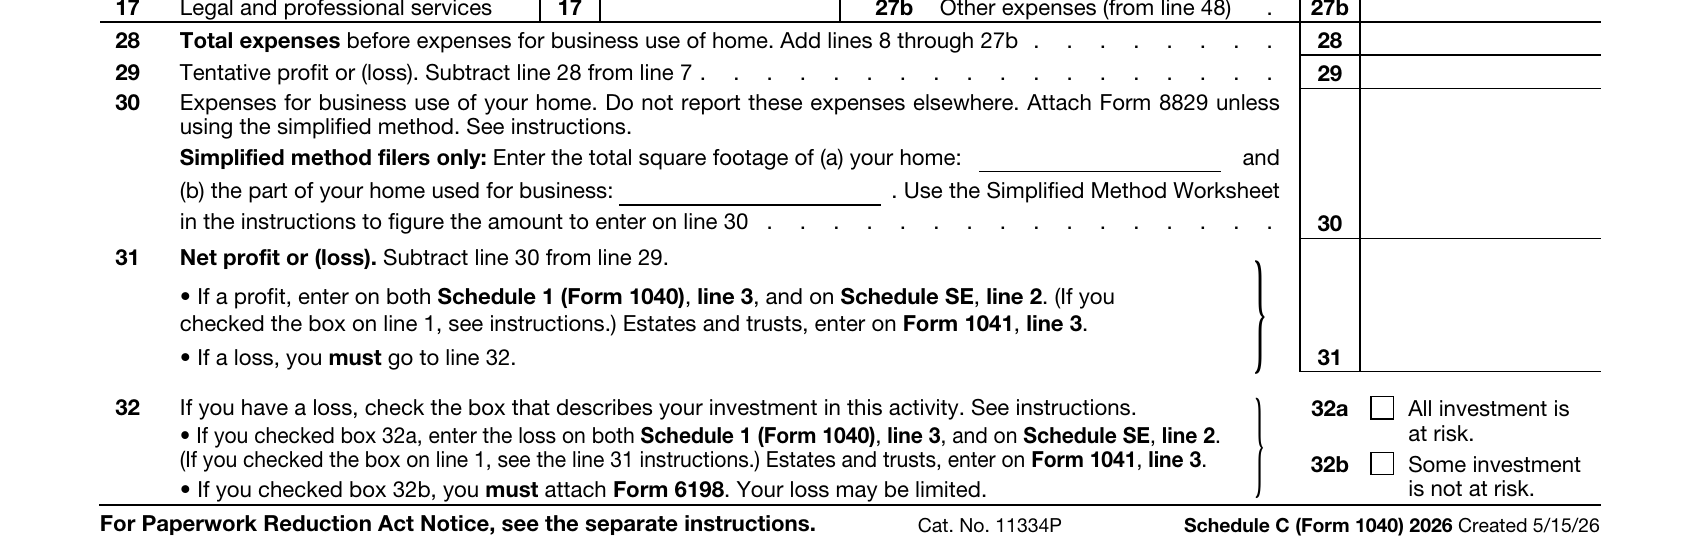
Line 28 adds the expense block. In the example: $3,240, plus $8,910, plus $6,300, plus $2,400, plus $1,980, plus $650, plus $1,120. That is $24,600.
Line 29 is tentative profit: line 7 minus line 28. $112,000 minus $24,600 is $87,400.
Line 30 is expenses for business use of the home — figured on Form 8829, or by the simplified method whose worksheet sits in the instructions. This example does not use it, so line 30 is zero. The home-office fork is its own article later this season; here the line is read as a zero and nothing more.
Line 31 is net profit: line 29 minus line 30. $87,400. And line 31 is a hand-off line — its own printed text names two destinations. For income tax, it enters Schedule 1, line 3. For self-employment tax, it enters Schedule SE, line 2 — the number Article 2 started from. This form figures the profit. It does not tax it. It sends it, twice.
§7Worked example: the whole form, in one table
Hypothetical real estate agent. Inputs are invented for this article; the line mechanics are the Schedule C 2026 draft as printed. The expense lines below are the only expenses in the example; every other Part II line is $0.
| Step | Schedule C line | Operation | Amount |
|---|---|---|---|
| Commissions (1099-NEC) | Line 1 — Gross receipts or sales | Hypothetical input | $112,000 |
| Returns and allowances | Line 2 | None in this example | $0 |
| Line 3 | $112,000 − $0 | $112,000 | |
| Cost of goods sold (from line 42) | Line 4 | No inventory in this example | $0 |
| Gross profit | Line 5 | $112,000 − $0 | $112,000 |
| Other income | Line 6 | None in this example | $0 |
| Gross income (core line) | Line 7 | $112,000 + $0 | $112,000 |
| Advertising | Line 8 | Example amount | $3,240 |
| Car and truck expenses | Line 9 | Entered amount only (build is Article 10) | $8,910 |
| Commissions and fees | Line 10 | Example amount | $6,300 |
| Contract labor | Line 11 | Example amount (see header items I/J) | $2,400 |
| Office expense | Line 18 | Example amount | $1,980 |
| Taxes and licenses | Line 23 | Example amount | $650 |
| Other expenses (from line 48) | Line 27b | Part V listing: MLS / association dues, totaled at line 48 | $1,120 |
| Total expenses | Line 28 | $3,240 + $8,910 + $6,300 + $2,400 + $1,980 + $650 + $1,120 | $24,600 |
| Tentative profit | Line 29 | $112,000 − $24,600 | $87,400 |
| Business use of home | Line 30 | Not used in this example | $0 |
| Net profit → Schedule 1, line 3; and Schedule SE, line 2 | Line 31 | $87,400 − $0 | $87,400 |
§8What this form does not cover
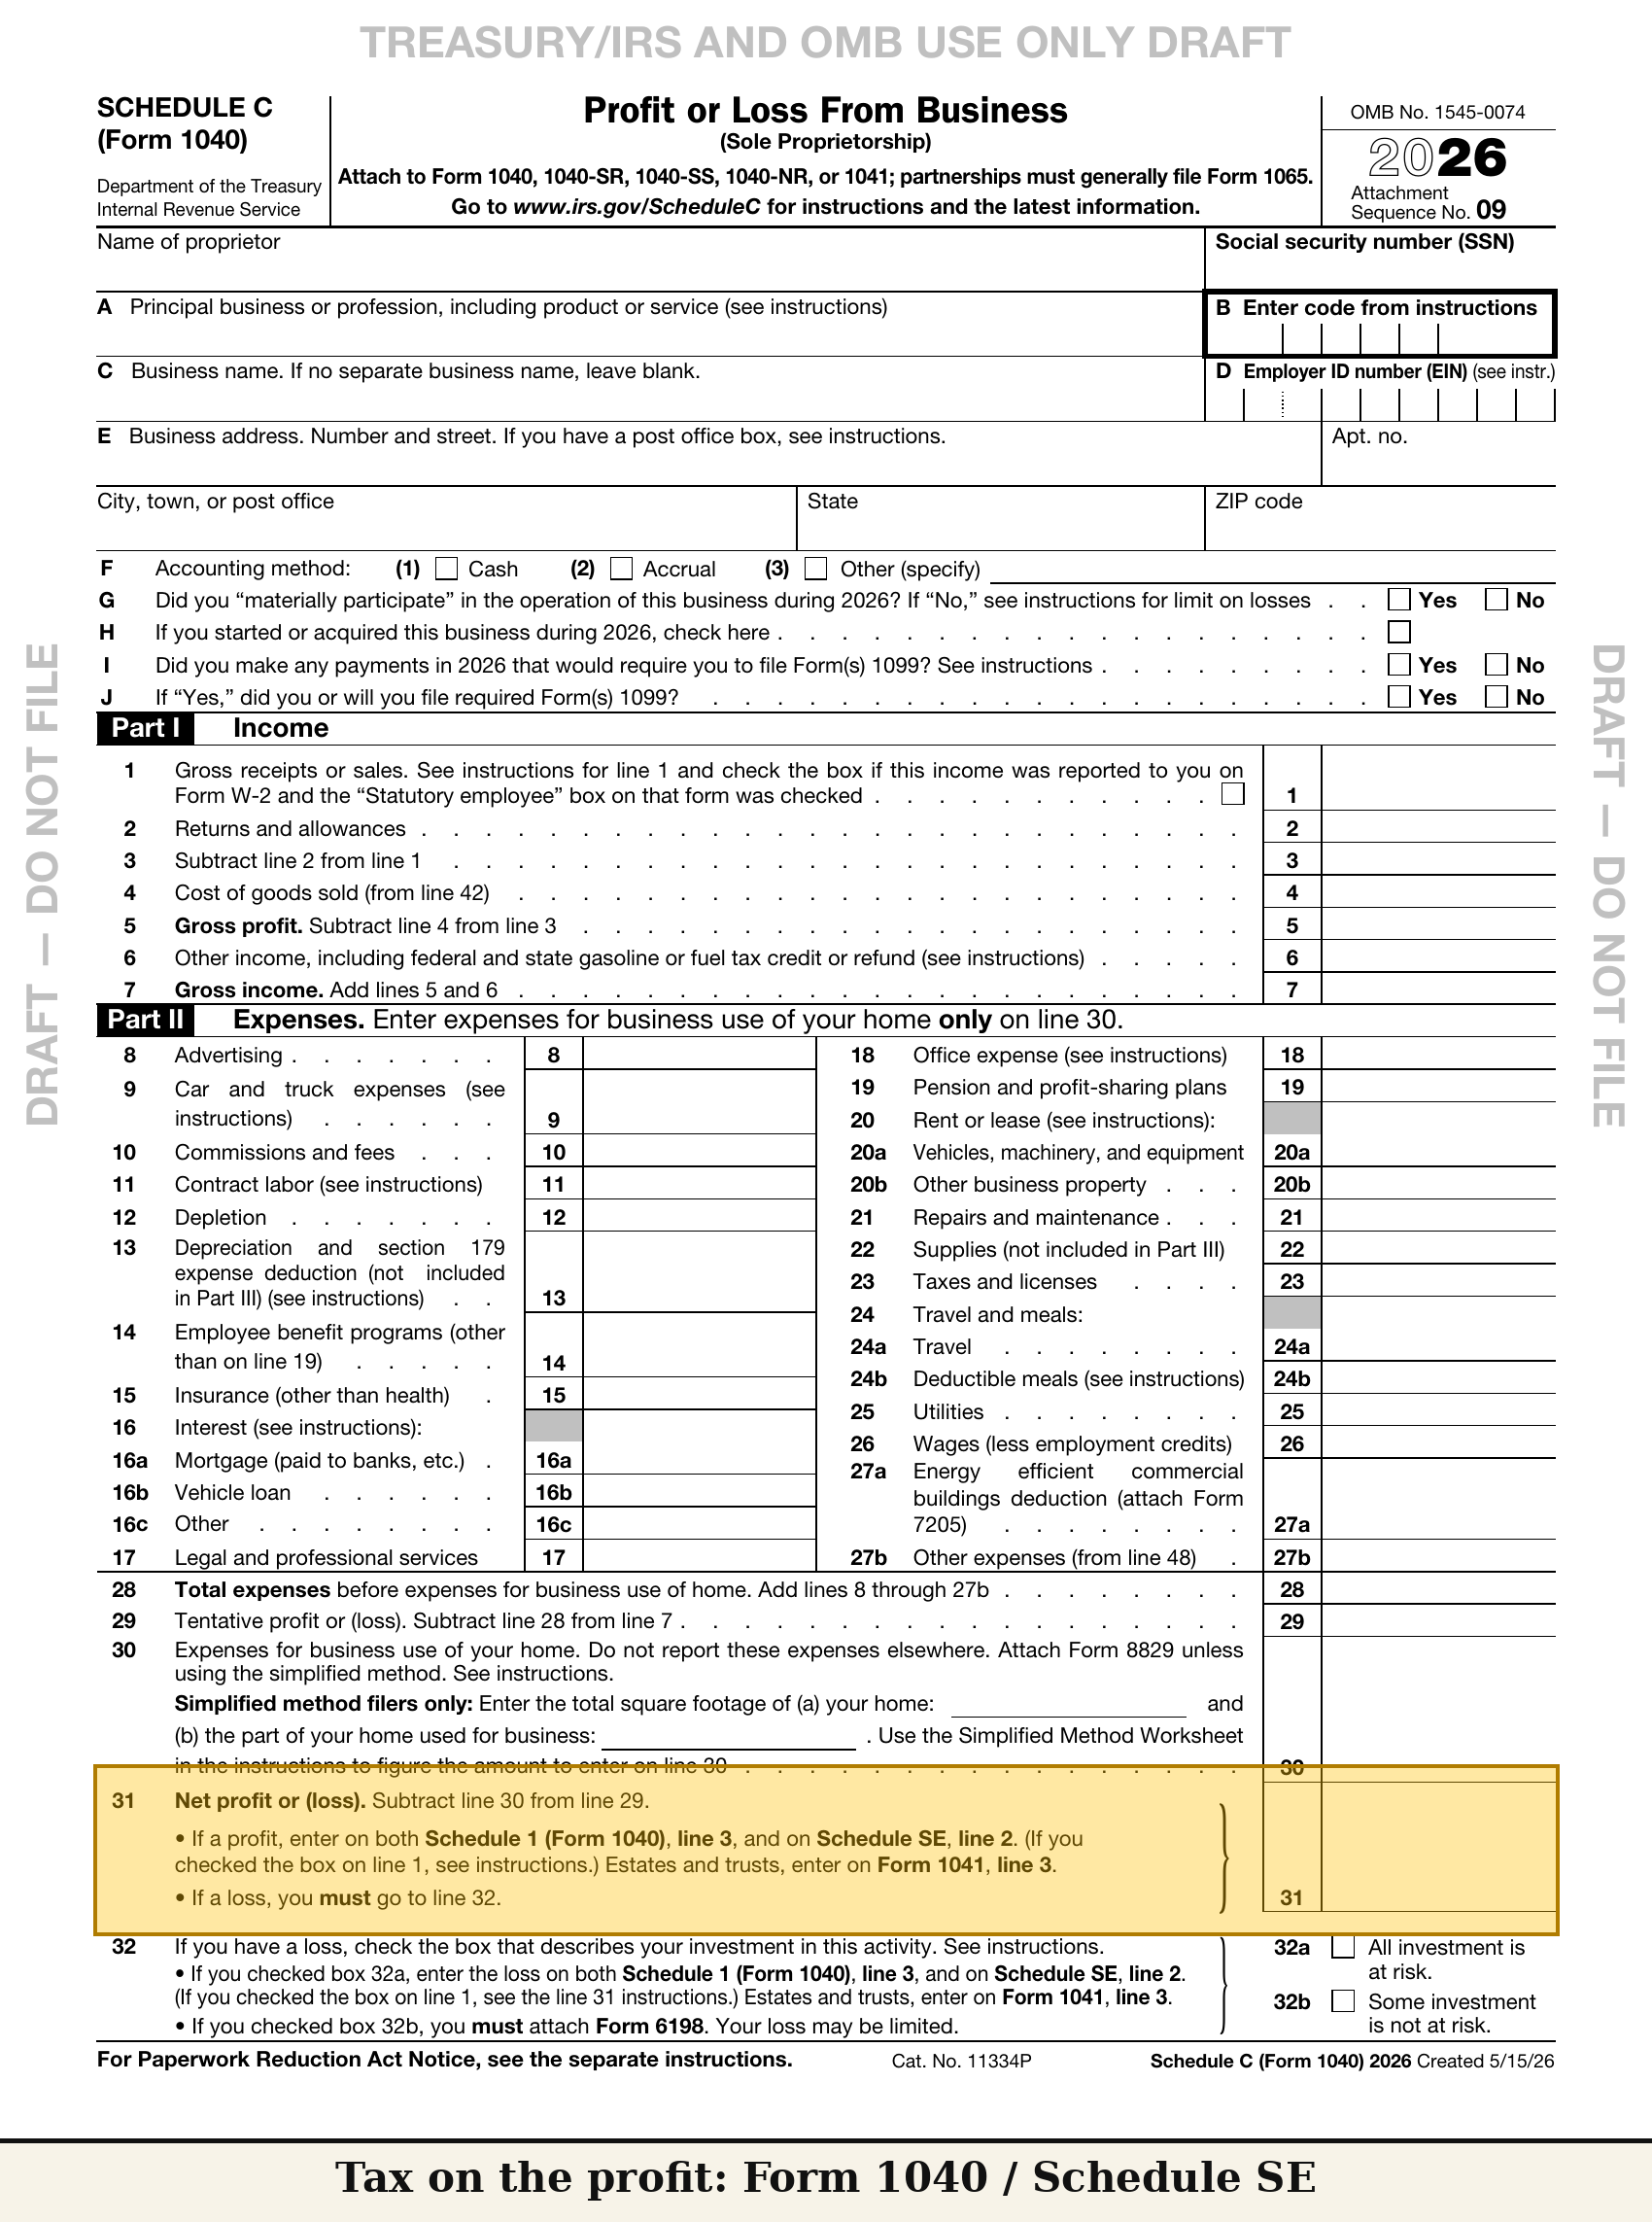
Schedule C full-page draft, greyed, with three callouts: "Tax on the profit: Form 1040 / Schedule SE" / "Estimated payments: Form 1040-ES" / "State taxes: not covered".
What Schedule C does not do, to close the reading.
It does not compute the tax on the $87,400. Income tax is figured on Form 1040 after Schedule 1 carries the profit in, and the self-employment tax on that same profit is Schedule SE's work — Article 2 read that chain line by line. It does not spread anything across the year: estimated payments are Form 1040-ES, Article 1's worksheet. It does not decide what counts as a business expense in the first place — it provides printed lines and a listing section, and the character of an amount is a question the form's labels frame but do not answer. And it does not touch state taxes. This site does not cover state taxes, in this article or any other.
§9Software numbers vs ask-a-human numbers
Every reading on this site ends by splitting the numbers in two — and a realtor's Schedule C splits cleanly.
One pile is pure arithmetic — a piece of software can carry the subtractions at lines 3 and 5, the addition at line 7, the total at line 28, and the two steps down to line 31, provided the amounts handed to it sit on the lines the form prints.
Numbers to take to a human before you act on them: whether an amount belongs on line 1 as a gross receipt or somewhere else entirely; whether a payment you made requires a Form 1099 under item I — the form asks the question, it does not answer it for your facts; and which printed line an unusual expense belongs on, or whether it belongs in the Part V listing at all.
That is Schedule C as the draft prints it for 2026: commissions in at line 1, gross income built at line 7 — $112,000 in this article's example — expenses totaled at line 28, and net profit of $87,400 leaving at line 31 for Schedule 1 and Schedule SE. IRS draft as of October 7, 2026.
Next article: Owner-Operator Taxes 2026: Schedule C Line 24b and the $80 Per Diem Day. (Article 6, in preparation)
Sources
7 claimsEvery claim above traces to a document, a tax year, a line, and the date it was checked.
-
1
Part I structure: line 1 gross receipts or sales; line 2 returns and allowances; line 3 = 1 − 2; line 4 cost of goods sold (from line 42); line 5 gross profit (3 − 4); line 6 other income; line 7 gross income (5 + 6)
- DOC
- Schedule C (Form 1040) (2026 draft, posted 05/28/2026), as printed in the full draft line map
- YEAR
- 2026 draft
- LINE
- Lines 1–7
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
2
Part II expense labels: line 8 advertising; line 9 car and truck expenses; line 10 commissions and fees; line 11 contract labor; line 18 office expense; line 23 taxes and licenses; line 27b other expenses (from line 48)
- DOC
- Schedule C (2026 draft)
- YEAR
- 2026 draft
- LINE
- Lines 8, 9, 10, 11, 18, 23, 27b
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
3
Line 28: total expenses, add lines 8 through 27b; line 29: tentative profit (7 − 28); line 30: expenses for business use of your home (Form 8829 unless simplified method; simplified-method worksheet is in the instructions, per the line's own text); line 31: net profit (29 − 30), entered on Schedule 1, line 3, and Schedule SE, line 2
- DOC
- Schedule C (2026 draft); cross-checked against Schedule 1 (2026 draft) line 3 and Schedule SE (2026 draft) line 2
- YEAR
- 2026 draft
- LINE
- Lines 28–31
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
4
Part V: other expenses are listed in Part V and totaled at line 48, which feeds line 27b
- DOC
- Schedule C (2026 draft)
- YEAR
- 2026 draft
- LINE
- Line 48 → line 27b
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
5
Header items I and J: item I asks whether the filer made payments in 2026 that would require filing Form(s) 1099; item J asks, if yes, whether the filer did or will file them
- DOC
- Schedule C (2026 draft), header
- YEAR
- 2026 draft
- LINE
- Items I, J
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
6
Part IV (vehicle information) is completed when claiming line 9 and not required to file Form 4562: line 43 date placed in service; line 44 miles (44a business / 44b commuting / 44c other); lines 47a–47b ask whether evidence exists and whether it is written
- DOC
- Schedule C (2026 draft)
- YEAR
- 2026 draft
- LINE
- Lines 43–47b
- CHECKED
- 2026-10-07 — IRS draft as of 2026-10-07
-
7
Title construction: job name leads, line number is a suffix at most, no deduction-listicle framing
- DOC
- Source registry Section I (YouTube suggest + competitor title evidence)
- YEAR
- Evidence checked 2026-10-07
- LINE
- Section I1, I2 clusters 4–5
- CHECKED
- 2026-10-07
Update log
Changes are dated and kept. Old figures are never silently overwritten.